


Japan’s inflation figures are next for a Yen stuck near 158.00
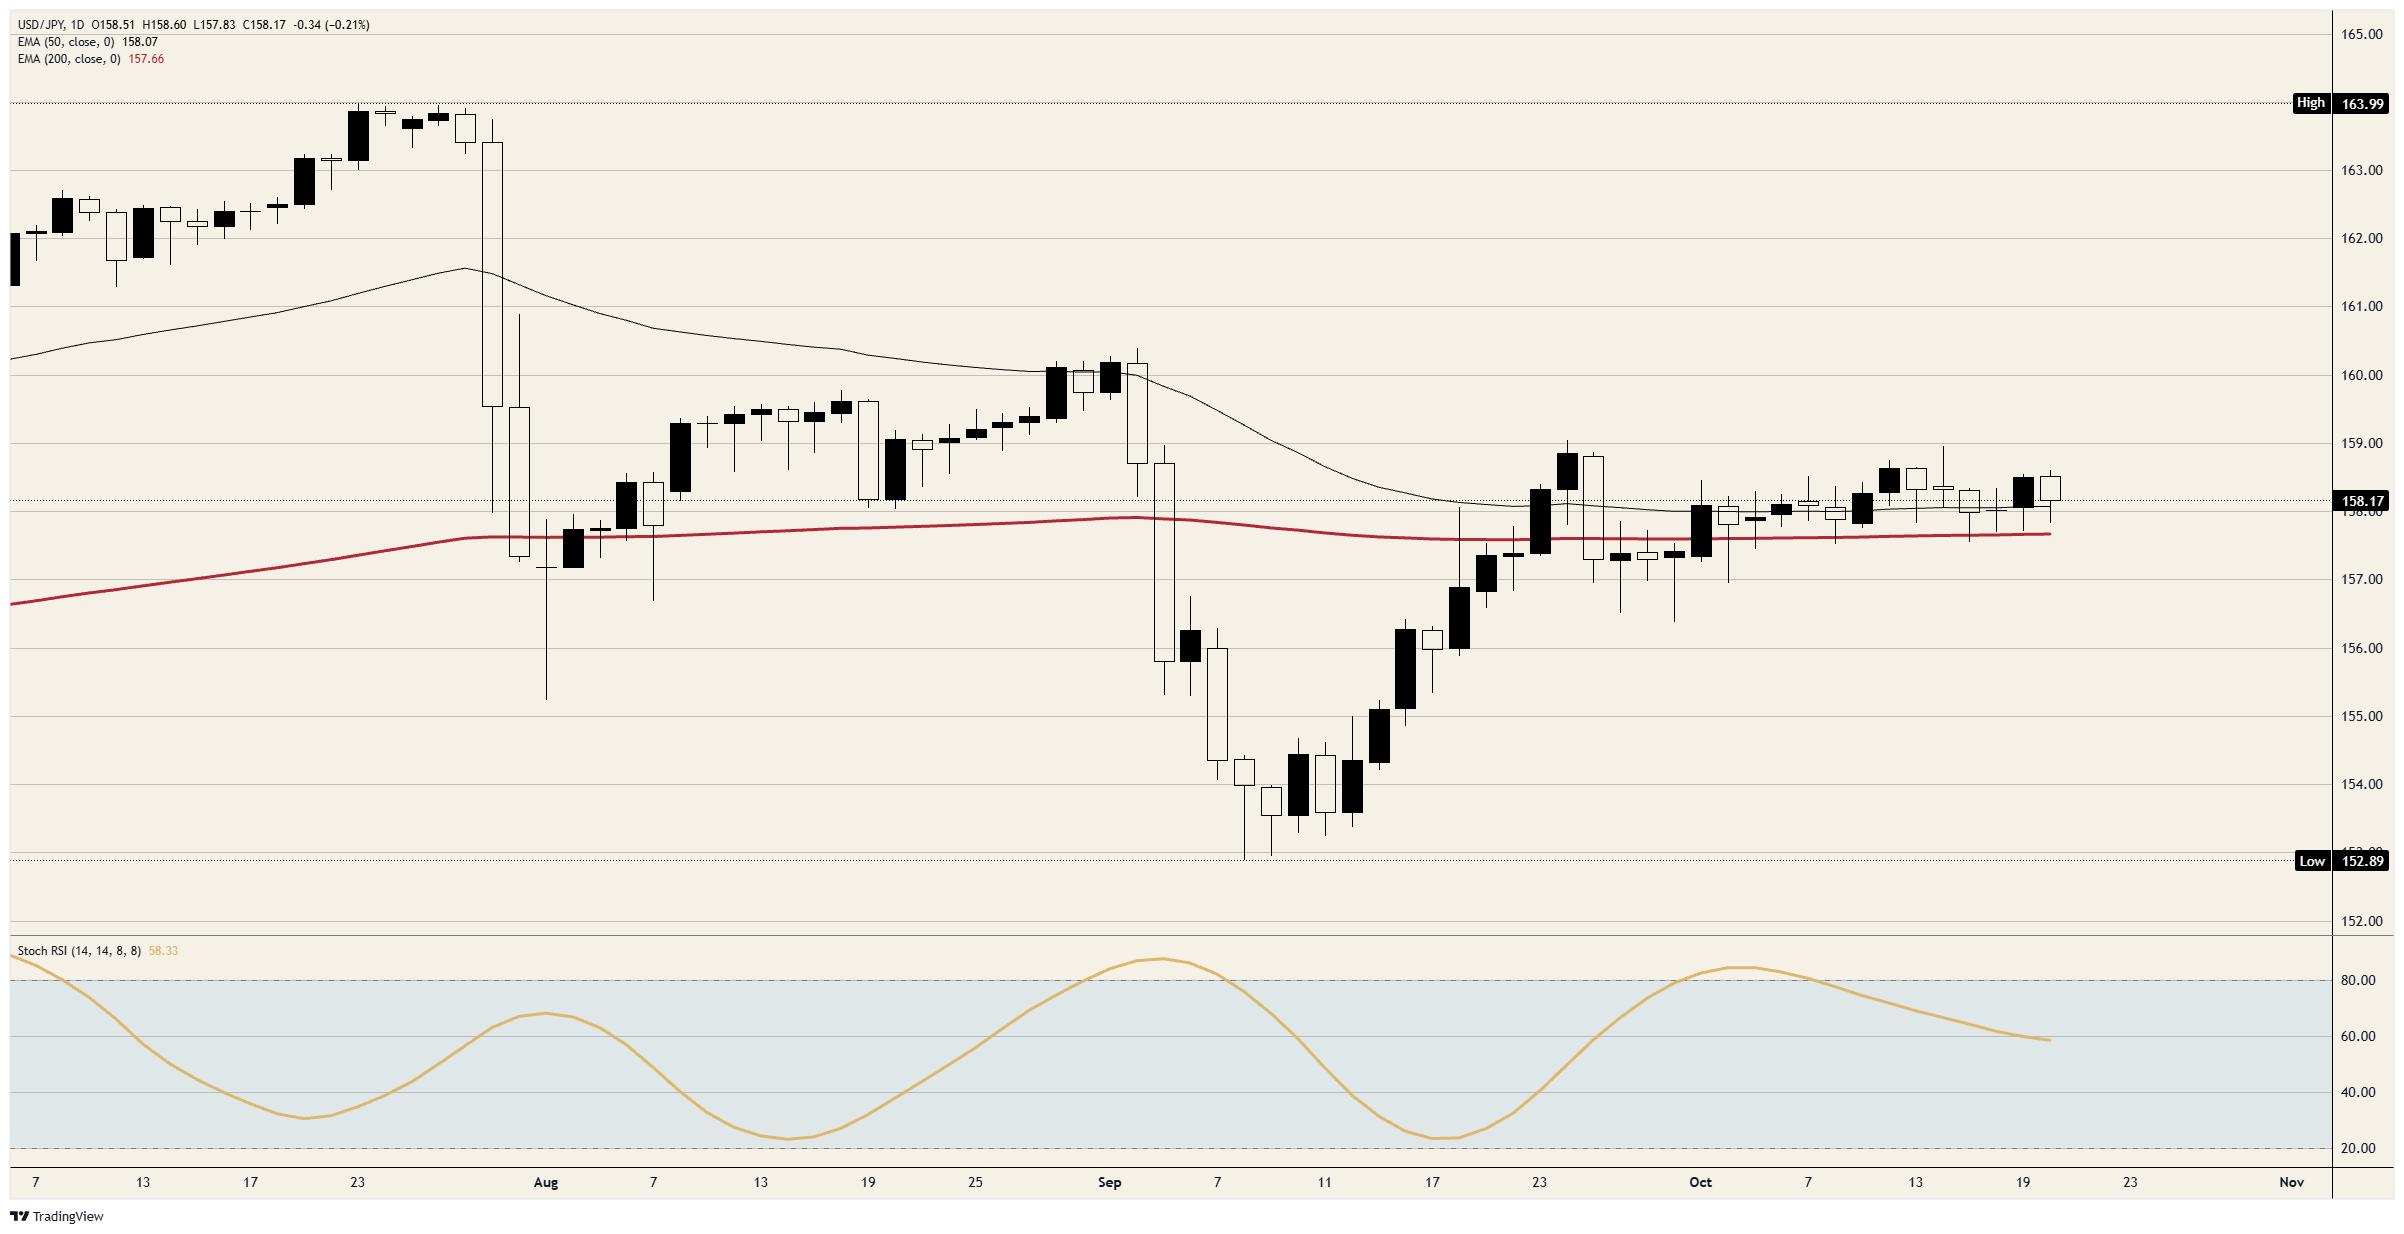
- USD/JPY ends near 158.00 again, inside the range it has held since October 1.
- Swaps put an October 30 BoJ hike under 5% and a December 18 hike near 80%.
- Japan's national CPI is due Thursday, ahead of the BoJ's October 30 decision.
Cheaper Crude Oil and a weaker Dollar elsewhere did little for the Yen on Tuesday, and USD/JPY ended about where it has ended most of October. It fell from about 158.50 to the session low and recovered about half of that drop.
Bank of Japan (BoJ) Governor Ueda told parliament on Monday that underlying inflation is very close to the 2% goal. In swaps, traders translated that into a less than 5% chance of a hike from 1.25% on October 30 and about 80% for December 18. That leaves Yen buyers no BoJ hike to price before December.
Prime Minister Takaichi rejected blame for the weak Yen, and Finance Minister Katayama said on October 15 that Japan is ready to act in the currency market again. Tuesday's high just above 158.50 is USD/JPY's highest since that warning, and it didn't hold.
On the calendar
Japan's September trade figures come at 23:50 GMT on Tuesday, with exports forecast up 20.1% from a year earlier after 19.3%. National CPI excluding fresh food follows at 23:30 GMT on Thursday, forecast at 2.1% after 1.7%, with the BoJ's 2% goal between the two.
University of Michigan one-year inflation expectations at 14:00 GMT on Friday are forecast unchanged at 4.7%, with five-year expectations at 3.5%. They're the last US inflation figures before the Fed's October 28 decision, two days before the BoJ's.
On the charts
Every daily close since October 1 has been within 75 pips of 158.00, with the 50-day Exponential Moving Average (EMA) within a few pips of it. The 200-day EMA is just above 157.50, and the October range runs from just under 157.00 to just under 159.00.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.